Benafica is a health benefits and insurance company that helps employers offer flexible, tax-free health reimbursement plans instead of traditional group health insurance.
ICHRA Eligible Expenses

Table of Contents
What ICHRA Can Reimburse
One of the most common questions employers have when designing an Individual Coverage Health Reimbursement Arrangement is straightforward: What exactly can employees use the money for? The answer depends on how you structure your plan. Understanding your options helps you build a benefit that genuinely serves your workforce while keeping your organization compliant with IRS rules.
Two Plan Design Options
When you set up an ICHRA, one of the most important design decisions is how broadly you want to define eligible expenses. The IRS gives employers meaningful flexibility here, and the choice has real implications for your employees’ purchasing power and your administrative complexity.
Option 1: Premiums-Only ICHRA
In a premiums-only plan, the ICHRA allowance can be used exclusively to reimburse individual health insurance premiums. This is the simpler of the two designs.
Eligible premiums under this structure include:
- Individual health insurance premiums (ACA marketplace or off-exchange plans)
- Medicare Part A premiums (if applicable)
- Medicare Part B premiums
- Medicare Part C (Medicare Advantage) premiums
- Medicare Part D (prescription drug coverage) premiums
- Medicare Supplement (Medigap) premiums
- Dental insurance premiums purchased as standalone individual policies
- Vision insurance premiums purchased as standalone individual policies
This design works well for employers who want to keep administration lean and focus the benefit squarely on helping employees secure coverage. Employees must still maintain Minimum Essential Coverage (MEC) to participate — more on that requirement below.
Option 2: Premiums + Qualified Medical Expenses
The more expansive design allows employees to use their ICHRA allowance for both insurance premiums and out-of-pocket qualified medical expenses as defined under IRC Section 213(d). This gives employees significantly more flexibility and is especially valuable for workers with high deductibles or recurring healthcare costs.
Employers who choose this design should be aware that it requires a more robust substantiation process, since employees must submit documentation for each expense claim. Platforms like Benafica’s BEN360 are designed to handle exactly this kind of claims tracking without adding significant administrative burden.
Eligible expenses under this structure include:
- Everything covered under premium-only (above); plus
Out-of-pocket medical costs
- Annual deductibles
- Copayments and coinsurance
- Emergency room fees not covered by insurance
- Ambulance services
- Lab tests and diagnostic fees
- Hospital bills and surgical costs
- Physical therapy
- Chiropractic care
Prescription drugs and medical devices
- Prescription medications (all categories)
- Insulin and diabetic supplies
- Over-the-counter medications (eligible since the CARES Act of 2020, no prescription required)
- Menstrual care products (eligible since the CARES Act of 2020)
- Hearing aids and batteries
- Eyeglasses and contact lenses
- Crutches, wheelchairs, and other durable medical equipment
- Breast pumps and lactation supplies
Dental and vision care
- Dental exams, cleanings, and X-rays
- Fillings, crowns, and oral surgery
- Orthodontia (braces and aligners)
- Dentures
- Eye exams
- Prescription eyeglasses and contact lenses
- LASIK and corrective eye surgery
Mental health services
- Psychiatrist and psychologist fees
- Psychotherapy and counseling
- Drug and alcohol addiction treatment
- Mental health facility services
Other qualifying services
- Acupuncture
- Smoking cessation programs (with physician certification)
- Weight loss programs prescribed by a physician for a specific disease
- Fertility treatments and in vitro fertilization
- Prenatal and postnatal care
- Vaccinations and immunizations
- Guide dogs (for visually or hearing impaired individuals)
- Home modifications required for medical reasons (e.g., wheelchair ramps)
What Is NOT an ICHRA Eligible Expense?
Equally important to understanding what qualifies is knowing what the IRS explicitly excludes. These expenses cannot be reimbursed through an ICHRA, regardless of the plan design:
- Cosmetic procedures — elective surgeries, teeth whitening, hair transplants, electrolysis
- Gym memberships and fitness programs — unless prescribed by a physician for a specific diagnosed condition
- General vitamins and nutritional supplements — unless prescribed for a diagnosed deficiency
- Maternity clothing
- Toiletries and personal hygiene products — toothbrushes, toothpaste, moisturizers
- Weight loss foods (as opposed to medically prescribed weight loss programs)
- Life insurance premiums or disability income insurance premiums
- Funeral or burial expenses
- Illegal treatments or substances
- Non-prescription contact lens insurance or vision discount plan premiums
This is not exhaustive — the full IRC Section 213(d) list is extensive — but it covers the core categories relevant to most employees.
About Minimum Essential Coverage (MEC)
Please note: If you’re considering an ICHRA with Benafica, you don’t have to worry about managing MEC requirements on your own. Our platform facilitates enrollment in MEC-compliant plans, and we handle the details around substantiation and reimbursement to help keep your ICHRA compliant.
Before an employee can receive any ICHRA reimbursement, they must be enrolled in a health plan that qualifies as Minimum Essential Coverage (MEC).
What Counts as MEC for ICHRA Purposes?
MEC-qualifying plans that are also eligible for ICHRA include:
- ACA-compliant individual healthplans purchased on or off the marketplace (bronze, silver, gold, or catastrophic tiers)
- Medicare Parts A and B together (Original Medicare)
- Medicare Part C (Medicare Advantage plans)
- Qualified student health insurance policies
- Coverage under certain catastrophic plans for eligible individuals
What Does NOT Qualify as MEC for ICHRA?
- A spouse's or parent's employer-sponsored group health plan
- COBRA continuation coverage
- Medicaid
- Short-term health plans
- Healthcare sharing ministry memberships
- Standalone dental or vision-only plans
- Preventive-only MEC plans (these fall short of ICHRA's requirements)
- TRICARE (eligible for some HRA types but not ICHRA)
Substantiation Requirements
The IRS requires that all ICHRA reimbursements be substantiated, meaning employees must provide documentation proving that each expense was incurred and qualifies for reimbursement. This applies to both proof of coverage and individual expense claims.
Proof of Coverage (Required for All Participants)
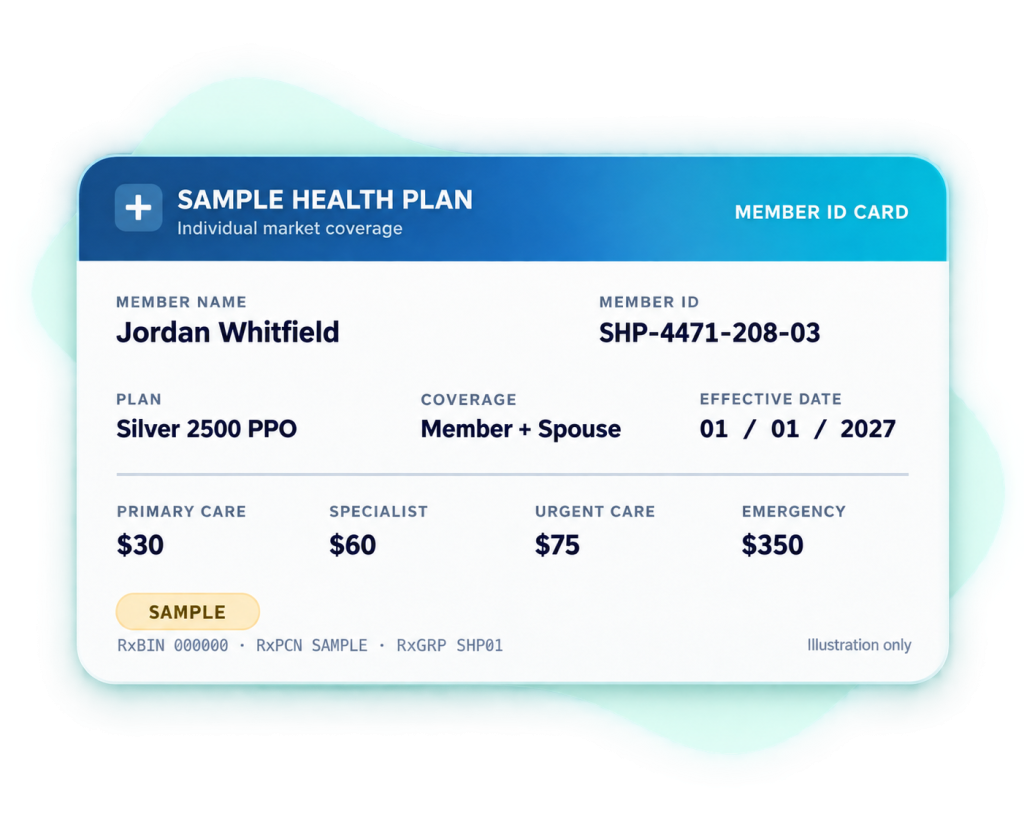
Before receiving any reimbursement, employees must demonstrate that they are enrolled in MEC-qualifying coverage. Acceptable documentation includes:
- Insurance card showing the individual's name and coverage details
- Explanation of Benefits (EOB) confirming active enrollment
- Written attestation specifying the covered individuals, the plan name, and the coverage start date
This verification must occur before the first reimbursement and should be confirmed at each plan renewal.
Proof of Expense (Required for Plans Covering Medical Expenses)
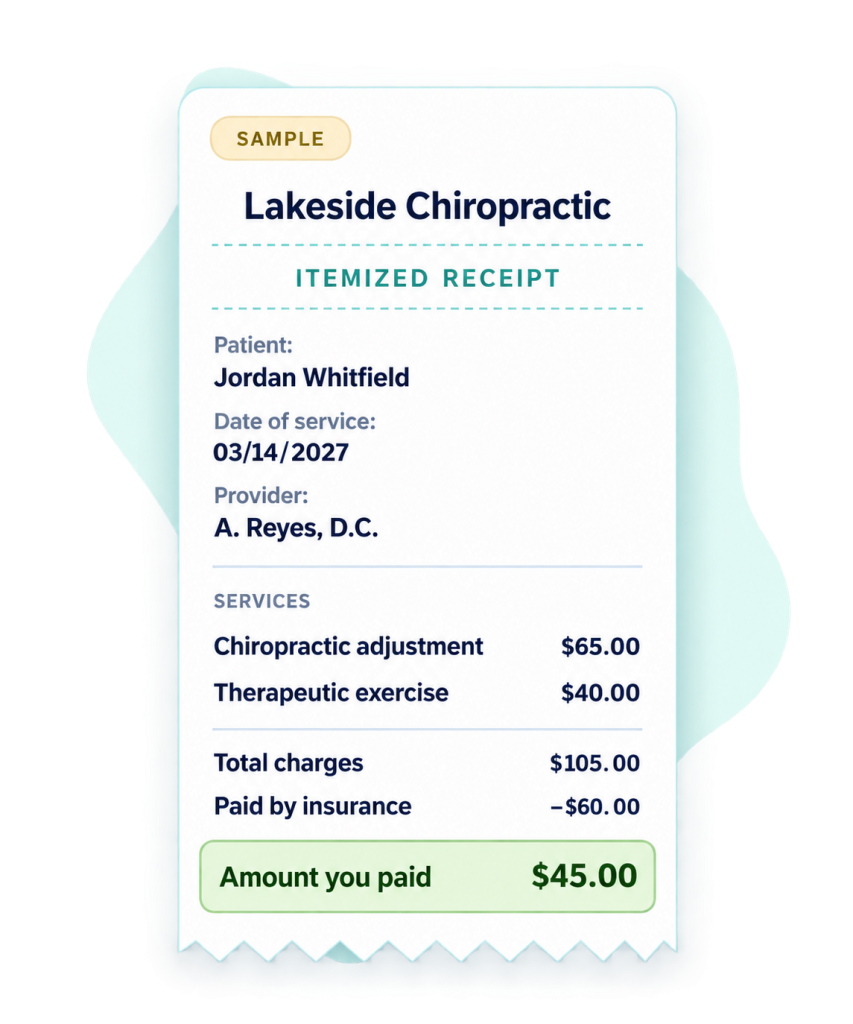
For ICHRAs that reimburse qualified medical expenses beyond premiums, employees must submit documentation for each individual claim. Acceptable documentation typically includes:
- Itemized receipts from the provider showing the date of service, description of service, and amount paid
- Explanation of Benefits (EOB) from the insurance carrier showing patient responsibility amounts
- Pharmacy receipts for prescription medications
Record Retention
Employers are responsible for maintaining substantiation records in accordance with IRS requirements. This documentation is essential in the event of an audit and confirms that the ICHRA is operating as a legitimate employer-sponsored benefit rather than a taxable compensation arrangement.
How BEN360 Simplifies Eligible Expense Tracking
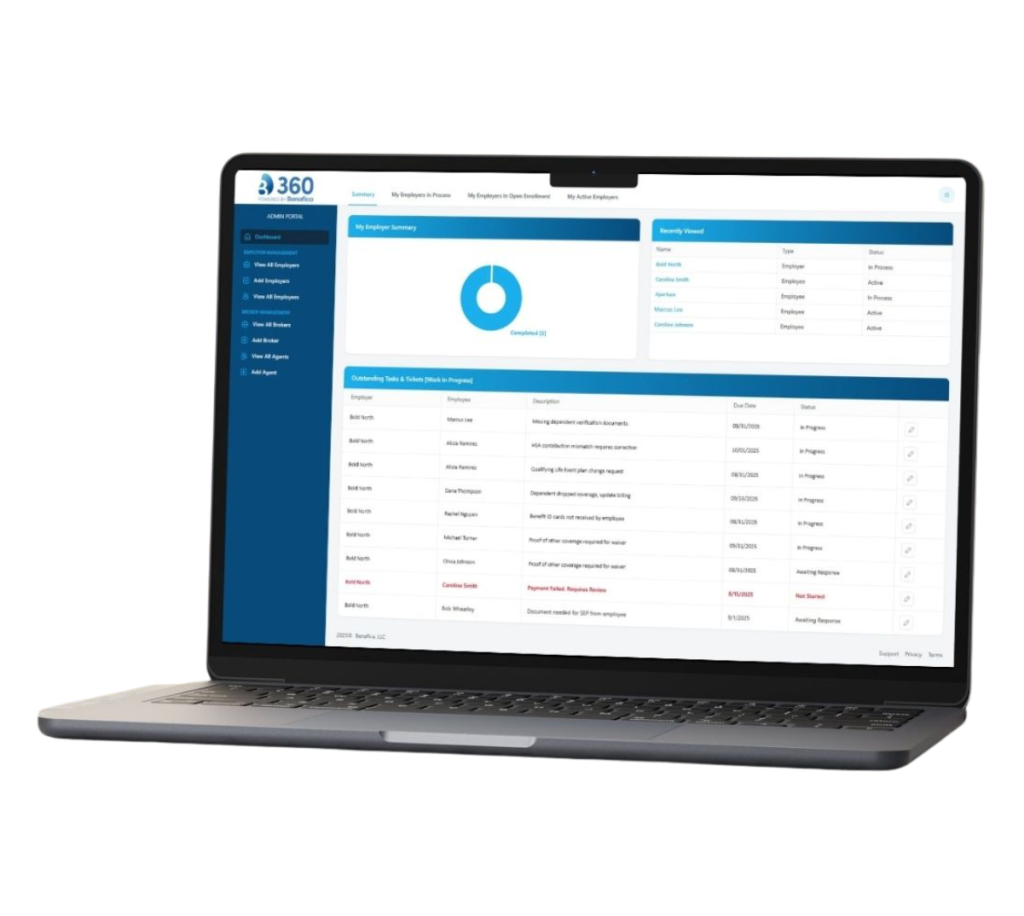
Our ICHRA platform, BEN360, is built specifically for ICHRA and HRA administration, and it handles the full expense tracking and claims workflow:
- Digital claims submission — employees upload receipts and supporting documentation directly through the portal, eliminating paper and email back-and-forth
- Automated eligibility verification — the platform confirms that each employee has qualifying MEC coverage before processing reimbursements
- Real-time allowance tracking — employees can see exactly how much of their annual allowance they've used and what remains
- Compliance-ready record keeping — BEN360 maintains a complete, audit-ready paper trail for every transaction
- Employer dashboard — plan administrators get a clear view of plan utilization, pending claims, and reimbursement history
Meet BEN360: Our ICHRA Platform
- Payment Transparency: Track every carrier payment to confirmation
- Enrollment Visibility: See who's enrolled, who's mid-application, and who hasn't started
- Year-Round Support: New hires, terminations, and qualifying life events handled by our team
Related ICHRA Guides
Ready to Build an ICHRA That Works?
Benafica has helped employers across Minnesota and beyond design, implement, and
administer ICHRAs that fit their workforce and their budget. From selecting the right plan
design to keeping your program compliant year after year, our team is with you every step of
the way
Benafica is an ICHRA and QSEHRA administration company and Third-Party Administrator (TPA) based in St. Paul, MN. This content is for educational purposes and does not constitute legal or tax advice. Expense eligibility depends on IRS rules and your plan’s terms, which may change. Consult your plan documents, a qualified tax professional, or legal counsel for guidance specific to your situation.