Benafica is a health benefits and insurance company that helps employers offer flexible, tax-free health reimbursement plans instead of traditional group health insurance.
ICHRA Employee Classes

On This Page:
What are ICHRA Employee Classes?
One of the most powerful features of an Individual Coverage HRA is the ability to divide your workforce into distinct employee classes and set different monthly allowance amounts for each one. The IRS defines 11 recognized classes, giving employers a structured, yet flexible, framework to tailor benefits to different groups of workers without running afoul of nondiscrimination rules.
The 11 ICHRA Employee Classes
| Class | Definition | Commonly Used For |
|---|---|---|
| Full-time employees | Generally defined as working an average of 30 or more hours per week (or 130 hours per month). | The core funded class in most designs |
| Part-time employees | Staff below your full-time threshold | Extending a benefit to people who previously got nothing |
| Salaried employees | Exempt, salaried staff | Employers who fund salaried and hourly differently |
| Hourly employees | Hourly staff | The other half of a salaried/hourly split |
| Seasonal employees | Staff hired for a defined seasonal period | Agriculture, retail peak, resort and tourism |
| Temporary employees of a staffing firm | The temporary-employee class exists for staffing firms offering coverage to the people they place. | Staffing and PEO-adjacent businesses |
| Collectively bargained employees | Employees covered by a union agreement | Keeping union coverage separate from everyone else |
| Employees in a waiting period | New hires who haven’t satisfied the eligibility waiting period | High-turnover roles where early attrition is common |
| Non-resident aliens with no U.S.-source income | Foreign workers with no U.S.-source income | Companies with overseas staff on U.S. payroll systems |
| Employees in the same rating area | Staff grouped by insurance rating area — typically state, sometimes county | Multi-state and multi-branch employers |
| A combination of 2+ of the above | Any two or more classes intersected | Nearly every real-world design (see below) |
Minimum Class Size Requirements
| Total Employees | Minimum Class Size |
|---|---|
| Fewer than 100 | 10 employees |
| 100 to 200 | 10% of total employees |
| More than 200 | 20 employees |
Variations Allowed Within Classes
Beyond class-level differences, employers may also adjust allowances within a class based on:
- Age — Allowances can vary by age at up to a 3:1 ratio (the oldest employee can receive up
to three times the allowance of the youngest employee). - Family status — Employers can offer higher allowances to employees with dependents
than to employees enrolled for self-only coverage.
When the Rules Don't Apply
- ICHRA-only employers: If you offer an ICHRA to all employees and no group plan to any class, minimum class size requirements do not apply at all.
- Waiting period combinations: If you combine a waiting period class with any other class, the minimum class size requirement for that combination is removed.
- State-level geographic classes: If the class is defined at the state level (e.g., "all employees in Minnesota"), no minimum class size requirement applies
Offering ICHRA and a Group Plan
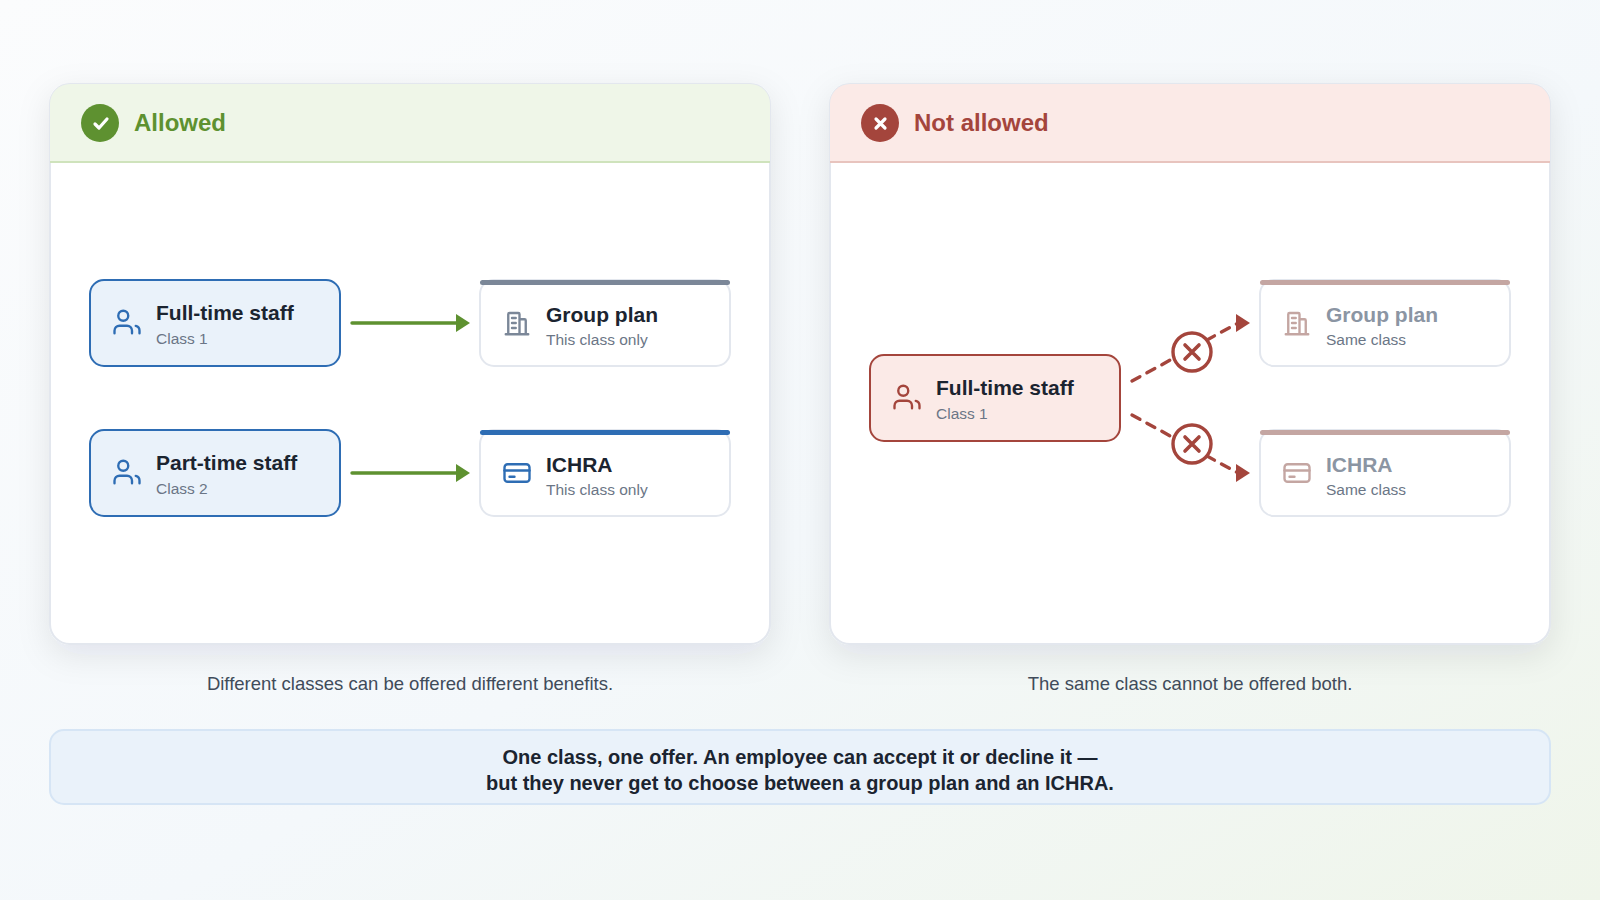
One rule that catches employers off guard: you cannot offer employees within the same class a choice between an ICHRA and a traditional group health plan. It’s one or the other, by class.
The most common structure by far: group plan for full-time staff, ICHRA for part-time or seasonal staff. It extends a real health benefit to people who were previously offered nothing, at a cost the employer controls, without disrupting the group plan the full-timers already like.
Real-World Class Designs
Full-time + rating area, part-time funded at a lower level
Four rooftops across two states, a mix of salaried sales staff, hourly technicians, and a part-time detail and porter crew that had never been offered coverage.
| Class | Definition used | Monthly allowance |
|---|---|---|
| Full-time — State A | Full-time + rating area | $650 |
| Full-time — State B | Full-time + rating area | $550 |
| Part-time | Part-time | $300 |
| Seasonal | Seasonal | Not funded |
Why it works: the rating-area split gives employees in both states comparable purchasing power without overpaying in the cheaper market. The part-time class converts a recruiting weakness into a differentiator.
Salaried + hourly split, group plan retained for tenured full-time staff
A long-tenured full-time workforce attached to an existing group plan, plus a growing part-time teller population and branches spread across several rating areas.
| Class | Definition used | Benefit |
|---|---|---|
| Full-time | Full-time | Existing group plan (unchanged) |
| Part-time | Part-time | ICHRA — $350/month |
| Waiting period | Waiting period + full-time | Not funded |
Why it works: nothing changes for the people most resistant to change. Confirm the part-time headcount clears the minimum class size threshold before committing to this structure.
Heavy part-time population, no group plan at all
Mostly hourly, high turnover, and a small salaried management team. No existing group plan, so minimum class sizes never come into play.
| Class | Definition used | Monthly allowance |
|---|---|---|
| Salaried management | Salaried + full-time | $700 |
| Full-time hourly | Non-salaried + full-time | $600 |
| Part-time hourly | Non-salaried + part-time | $350 |
| New hires | Waiting period | Not funded until 60 days |
Why it works: the waiting-period class absorbs early-attrition turnover without a wasted allowance, and the three funded tiers scale cleanly with the compensation structure that already exists.
Guardrails and Common Mistakes
ICHRA employee classes give employers flexibility, but they can’t be used to pick and choose which individual employees receive benefits. Classes must be based on legitimate, job-based criteria and applied consistently. Avoid creating classes based on health status, expected medical costs, or other factors designed to separate higher-cost employees from the group plan.
- Building a class around a person
- Inventing a class
- Varying allowances inside a class (except the permitted variances)
- Offering a choice between group and ICHRA
- Forgetting the minimum class size math
- Ignoring affordability for ALEs
Class Design and Affordability
If your company has 50 or more full-time equivalent employees, the ACA employer mandate requires you to offer affordable, minimum-value coverage or risk significant penalties under Section 4980H. An ICHRA can satisfy this mandate, but affordability calculations must be performed at the class level using the lowest-cost silver plan available in each employee’s rating area.
The friction point is usually the same one: a class that mixes high and low earners at a single flat allowance can be affordable for one group and unaffordable for the other. Splitting that class (often by salaried versus non-salaried) is frequently the fix.
Go Deeper: Affordability calculation, the IRS safe harbors, and how an unaffordable offer interacts with premium tax credits are covered in full on ICHRA affordability.
Employee Classes FAQ
How many employee classes can I create?
There’s no cap on how many classes you use, but you’re limited to the 11 permitted definitions and combinations of them. Practically, most employers land on two to five; beyond that, administration and communication get harder faster than the design gets better.
Can I create a class based on job title or department?
No. Job title, department, tenure, and performance are not permitted class definitions. If you need to differentiate along those lines, look for a permitted class that correlates (salaried versus non-salaried often does).
Can I offer different allowances to employees in the same class?
Only by age and family size. Every other variation within a class is off-limits.
Do I have to fund every class?
No. You can define a class and offer it nothing. For example, seasonal employees and employees in a waiting period are commonly left unfunded.
Can an employee move between classes?
Yes, when their circumstances change. A part-time employee promoted to full-time moves into the full-time class, and a new hire moves out of the waiting-period class automatically. The change is processed as an ICHRA event.
Do minimum class sizes apply if I don't offer a group plan?
No. Minimum class sizes only come into play when a traditional group plan is offered to one class and an ICHRA to another.
How do classes work for a multi-state employer?
The rating area class exists for exactly this. Combine it with full-time or salaried status to give employees in each market comparable purchasing power, since individual premiums vary widely by geography.
Can I change my classes next plan year?
Yes. Class structure is set per plan year, so you can restructure at renewal. Mid-year changes are more constrained — talk to us before making one.
What counts as full-time for ICHRA purposes?
You define it in your plan document, but it has to be applied consistently. It’s generally defined as working an average of 30 or more hours per week (or 130 hours per month).
Can family members be in a different class than the employee?
No. Classes apply to employees. Family size affects the allowance amount within a class, not class membership.
Related ICHRA Guides
Not Sure How to Structure Your Classes?
Send us your census (headcount, age, and locations) and we’ll model two or three class structures against your current spend so you can see the trade-offs side by side.